Concept designConcept design. Fictional business, not client work.By Press Row Studio
Office hours: weekdays 8:30 a.m. to 5:30 p.m.Haskett Insurance Agency · North Main Street, Hutchinson, KansasHutchinson, Kansas

Haskett Insurance · Business

Your business policy has letters too.

General liability is written in Coverages A, B and C. Property, workers’ comp and the truck are separate policies that sit beside it. Ray sorts out which one owns which risk.

PRAIRIE MERCANTILEOPEN

Tap a letter on the drawing or below to see what it covers.

Which policy owns which risk.

The three lettered parts of general liability, then the three policies most Kansas businesses add beside it.

Drawing, not to scale

Coverage A: Injury and damage

General liability’s Coverage A pays when your business injures someone or damages their property: a customer trips on a mat, a crew member cracks a client’s countertop.

Often missed. It doesn’t cover your own employees (that’s workers’ comp) or your own vehicles (commercial auto).

Coverage B: Advertising injury

Coverage B is for injuries that aren’t physical: a claim that your ad copied someone else’s, or that something you said or posted damaged a reputation.

Often missed. It isn’t a cyber policy and it doesn’t cover patent or trademark fights.

Coverage C: Medical payments

Coverage C pays a customer’s medical bills after an injury on your premises, without anyone having to prove fault. Often it keeps a small accident from becoming a lawsuit.

Often missed. Never your employees. Their injuries are workers’ comp.

Property

Your building if you own it, plus what’s inside: fixtures, inventory, tools, computers. Often packaged with liability in a business owner’s policy (BOP).

Often missed. Ask about business income coverage, which can replace lost income while you’re closed after a covered loss.

Workers’ comp

Medical care and lost wages for employees hurt on the job, and it generally takes the place of a lawsuit against you over those injuries.

Often missed. In Kansas, most employers with more than $20,000 in annual gross payroll must carry it. Family-member wages and some farm work are treated differently.

Commercial auto

Covers vehicles the business owns, and can extend to employees driving their own cars on business errands (hired and non-owned auto).

Often missed. A personal auto policy may not cover a vehicle used mainly for business. Tell us how the truck is really used.

Do you need workers’ comp in Kansas?

The Kansas rule is about payroll, not headcount. Slide to your yearly gross payroll.

Wages paid to family members of the owner don’t count toward the line, and some agricultural work is exempt. If you’re close, call Ray before you hire.

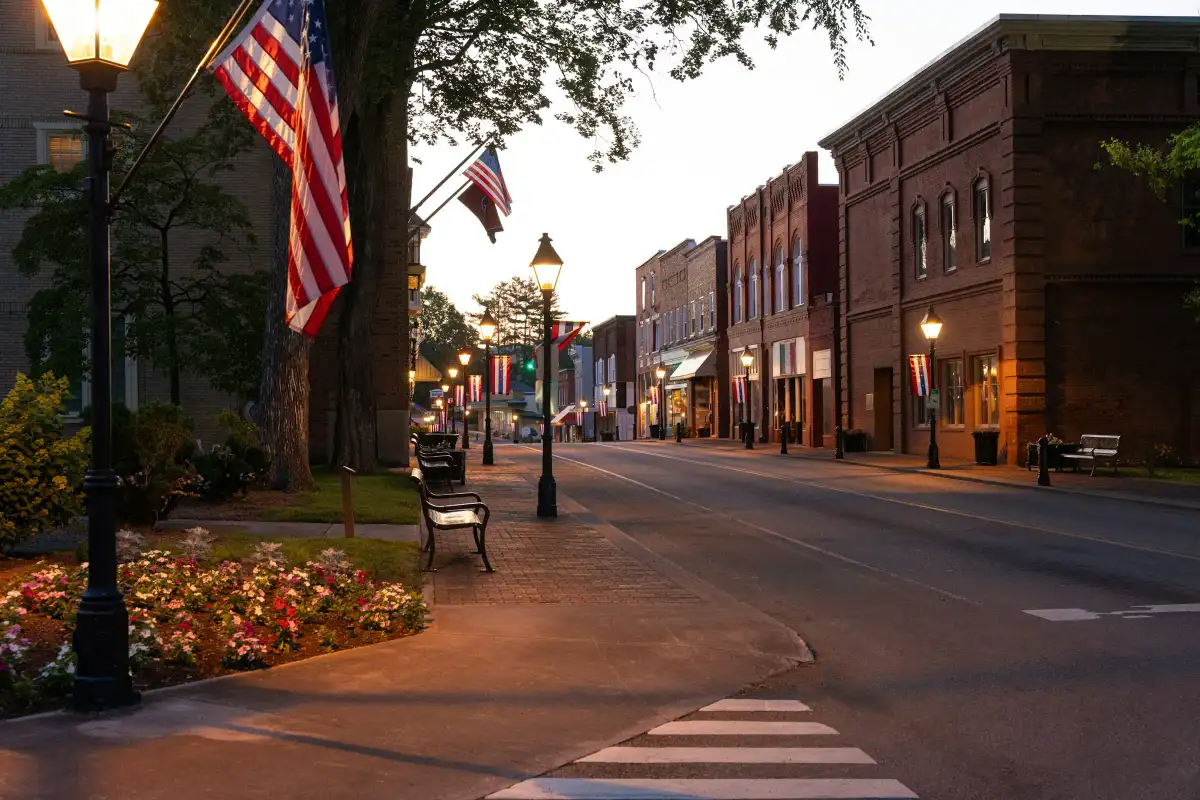
A small-town main street at dusk with flags, street lamps and brick storefronts
Stock photo, not Hutchinson
$35,000

Over $20,000: Kansas generally requires workers’ comp. Coverage has to be in place for your employees, and work injuries get reported to the Department of Labor.

Source: Kansas Department of Labor, Workers Compensation. A general guide, not legal advice.

Certificates of insurance, same day.

A general contractor or a landlord wants proof you’re covered before you start. Email Ray the job name and who needs the certificate; ask before 3 p.m. and it goes out that afternoon.

  • Shops and storefronts. Main Street retail, salons, restaurants. Usually a business owner’s policy plus workers’ comp.
  • Contractors and trades. General liability with certificates for every job, tools coverage, commercial auto for the trucks.
  • Offices. Accountants, real estate, clinics. Property, liability, and professional liability where your field needs it.
  • Farm-adjacent businesses. Custom harvest, hauling, seed dealers. Mixed vehicle and liability needs; we sort out which policy owns which risk.

Certificate of insurance

Sample, for a fictional business. Not a real policy.

Named insured
Prairie Line Remodeling LLC
Certificate holder
The general contractor on your job
General liability
ABC each occurrence and aggregate limits listed
Workers’ comp
Kansas statutory coverage
Commercial auto
Owned, hired and non-owned autos

A certificate shows coverage on the day it’s issued. It doesn’t change the policy.

Let Ray look at what you carry.

Bring your current policies or a recent audit. We’ll show you the gaps, then quote several carriers.

CallTalk to Ray